Table of Contents
TL;DR
Income creates opportunity, but it does not guarantee wealth. A doctor earning $350,000 can still trail a teacher earning $55,000 when student debt, delayed investing and expensive lifestyle choices absorb the advantage. An entrepreneur may build far greater net worth through business equity, but that wealth can be risky and difficult to access. The balance sheet tells the real story.
Why Income Level Is a Poor Predictor of Net Worth
A high salary makes wealth building easier. It provides more room to save, invest, buy property and recover from financial mistakes. But salary is not the same as net worth.
Net worth measures what remains after adding every asset and subtracting every liability:
Net Worth = Total Assets − Total Liabilities
According to the Federal Reserve’s 2022 Survey of Consumer Finances, the median net worth for families with a reference person aged 35 to 44 was $135,600. The same report shows that wealth generally rises with income, but it does not say that occupation or salary automatically determines an individual household’s outcome.
That distinction matters. A doctor may start earning a high salary after years of training and substantial student debt. A teacher may begin saving and building home equity nearly a decade earlier. An entrepreneur may earn less than either person during some years, while building ownership in a business that later becomes valuable.
The following three profiles are not national averages. They are modeled balance sheets showing how someone can reach age 40 with a very different financial position from what their salary suggests.
Persona 1: The Doctor at 40
The Income Story
A physician completes training and begins earning $350,000 annually at age 32. By age 40, the doctor has had eight high-income years. From the outside, this may look like an automatic path to financial independence.
But the high salary started late. During the years when many other professionals were making retirement contributions, paying down a first mortgage or accumulating investments, the doctor was completing medical training and carrying education debt.
The Balance Sheet Reality
Assume the doctor began the higher-income years with approximately $280,000 in student loans. Income then supported a $1.2 million home, two high-end vehicles and increased family expenses. The doctor has invested consistently since becoming an attending physician, but debt and lifestyle costs have limited the result.
| Doctor’s Balance Sheet at 40 | Amount |
| Primary home value | $1,200,000 |
| Retirement and brokerage investments | $330,000 |
| Cash reserves | $60,000 |
| Vehicle resale value | $90,000 |
| Total assets | $1,680,000 |
| Mortgage balance | -$1,010,000 |
| Remaining student loans | -$230,000 |
| Auto loans | -$60,000 |
| Total liabilities | -$1,300,000 |
| Net worth | $380,000 |
A $380,000 net worth at age 40 is still well above the Federal Reserve median for the 35-to-44 age group. The surprising part is that it may be lower than people expect from a $350,000 income.
The doctor has strong future earning potential. But a large mortgage, remaining student debt and financed vehicles show how quickly high income can become tied to liabilities. The next decade may be powerful for wealth building, but only when increased earnings begin flowing more aggressively into investments and debt reduction.
Persona 2: The Teacher at 40
The Income Story
A teacher starts working at age 22 and earns an average income that reaches approximately $55,000 annually by age 40. The salary never approaches the doctor’s. However, the teacher begins building assets ten years earlier.
At 23, the teacher starts making steady Roth IRA contributions, increasing them as income allows and remaining within annual contribution limits. At 26, the teacher buys a modest home and spends the next 14 years paying down the mortgage. A pension or cash-balance benefit provided through employment also begins adding long-term value.
The Balance Sheet Reality
This teacher avoids expensive consumer debt, drives a practical vehicle and directs raises toward retirement contributions and mortgage payments rather than major lifestyle upgrades.
| Teacher’s Balance Sheet at 40 | Amount |
| Modest primary home value | $290,000 |
| Roth IRA and other investments | $155,000 |
| Documented pension or cash-balance value | $70,000 |
| Emergency savings | $20,000 |
| Vehicle resale value | $12,000 |
| Total assets | $547,000 |
| Mortgage balance | -$110,000 |
| Auto loan | -$8,000 |
| Remaining student loan balance | -$9,000 |
| Total liabilities | -$127,000 |
| Net worth | $420,000 |
The teacher earns far less than the doctor, yet has a modeled net worth that is $40,000 higher.
Time made much of the difference. Fourteen years of homeownership allowed equity to build. Seventeen years of retirement investing gave contributions more time to grow. Keeping debt and housing costs modest left more of each paycheck available for assets.
A pension needs careful treatment in a net worth calculation. Include it as a current asset only when a plan statement provides a cash-balance, lump-sum or reasonable present-value figure. A future monthly pension benefit is financially valuable, but it should not be casually assigned an unsupported dollar value.
The teacher’s story does not prove that lower income is better. It shows that starting earlier, controlling major costs and contributing consistently can overcome a large income gap for a meaningful period of time.
Persona 3: The Entrepreneur at 40
The Income Story
An entrepreneur has the least predictable income of the three. Some years produce only $30,000 in personal income. Better years bring $200,000 or more. Instead of maximizing retirement accounts early, much of the available cash is reinvested into building a software business.
At age 40, an outside valuation places the entrepreneur’s ownership stake in the business at $800,000 after business liabilities are accounted for. That valuation is an assumption based on business performance and buyer demand, not guaranteed cash in a bank account.
The Balance Sheet Reality
| Entrepreneur’s Balance Sheet at 40 | Amount |
| Net business equity | $800,000 |
| Home equity | $70,000 |
| Cash reserves | $40,000 |
| Brokerage and retirement investments | $60,000 |
| Vehicle equity | $10,000 |
| Personal tax balance owed | -$30,000 |
| Net worth | $950,000 |
The entrepreneur’s net worth is far higher than either the doctor or the teacher. But it is also more concentrated. Approximately 84% of the entrepreneur’s net worth sits in one private business.
Business equity can be an extraordinary wealth builder. It can also be difficult to sell, vulnerable to competition and dependent on future revenue. If the business loses customers or market valuations fall, the entrepreneur’s paper net worth can decline rapidly.
This person may have the highest net worth at 40 while still needing a clear plan to build cash reserves, retirement assets and diversified investments outside the business.
Three Lessons From These Balance Sheets
Time Gives Moderate Income More Power
The teacher’s advantage comes partly from beginning earlier. Investing and building home equity from the early 20s can create a strong foundation before a higher earner has completed training or eliminated education debt.
That does not mean early investing always beats high income. A doctor who controls lifestyle costs and invests heavily can rapidly close the gap. The lesson is that delayed investing creates ground that must later be recovered.
Keeping Major Costs Controlled Matters at Every Income
Frugality does not mean avoiding every comfort. It means keeping housing, vehicles and recurring debt from consuming the income that could be building assets.
A $350,000 income attached to a large mortgage, student loans and vehicle debt can produce less net worth than a $55,000 income paired with steady investing and manageable living costs. Earning more helps most when spending does not rise just as quickly.
Business Equity Can Build Wealth but Also Concentrates Risk
The entrepreneur’s business stake creates the largest net worth in this comparison. It also creates the greatest dependence on one asset.
Entrepreneurs should value business ownership conservatively and build assets outside the company over time. A business may be worth $800,000 on paper, but retirement savings and accessible investments provide financial strength that does not depend on finding a buyer for one company.
Where Do You Stand?
Comparing salaries tells you very little about your actual financial position. Your balance sheet is the useful comparison.
List your cash, retirement accounts, investments, real estate equity, business value and other meaningful assets. Then subtract student loans, mortgages, auto debt, credit cards, tax balances and any other liabilities. Use the resulting number to ask: where do you stand?
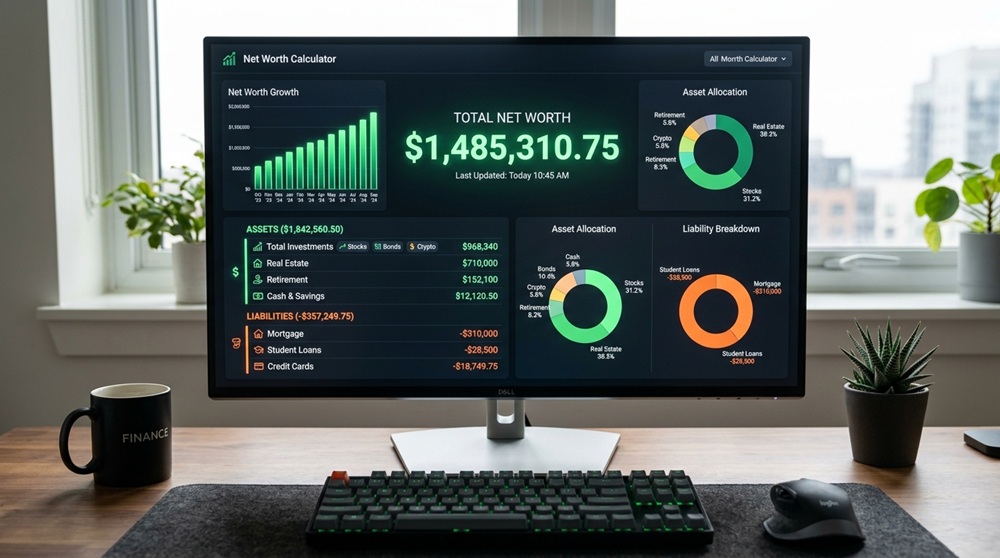
The calculator lets you enter assets and liabilities, see your net worth immediately and compare the result with a U.S. age benchmark. For someone aged 40, the relevant Federal Reserve median family net worth benchmark is $135,600 for the 35-to-44 age group.
A benchmark is not a verdict. The doctor, teacher and entrepreneur in these examples all exceed the median, yet each faces a different next move. The doctor may prioritize debt and investment growth. The teacher may strengthen liquid savings alongside retirement planning. The entrepreneur may need to diversify wealth beyond the business.
Further guidance on tracking assets, debts and personal wealth is available through NetlyWorth.
Build the Balance Sheet, Not Just the Income Statement
Income can open doors, but it is only a starting resource. Net worth shows what you have built with that income, how much debt remains and how concentrated your financial future may be. Track the full picture, make decisions that increase assets rather than appearances, and judge progress by the balance sheet you are creating over time.